
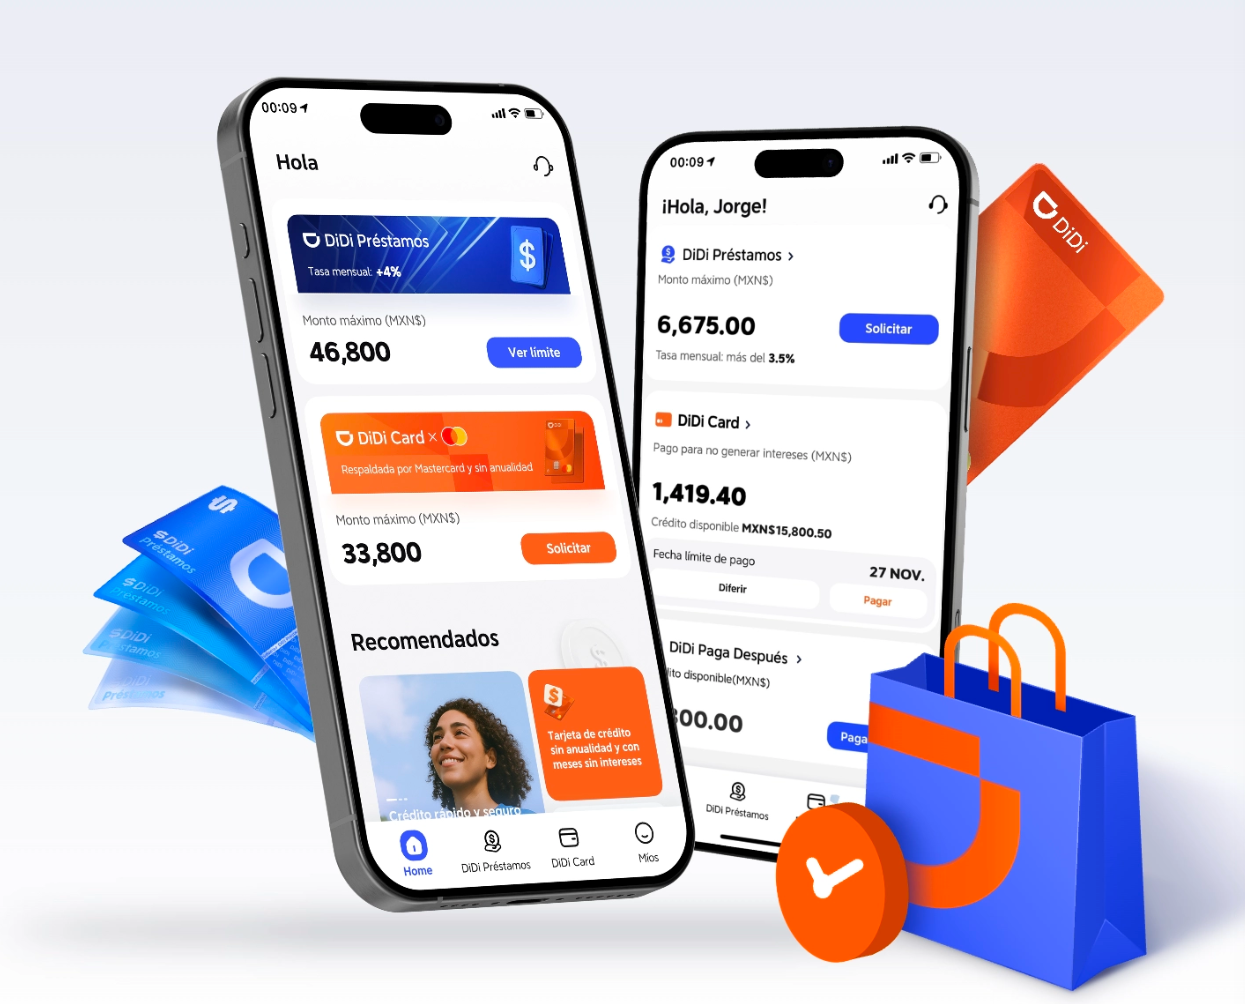
Simple start: what this means for you
People who ride or drive and people who shop want extra money back. This piece looks at how DiDi card cashback fits into that world. It talks like a friend and shows what a traveler in Mexico City might notice about fares, rewards, and payment choices. You can peek at didi finanzas if you want a direct place to explore the card and its offers.
How cashback cards work, in plain play
Cashback is a tiny return when you pay with a credit card. You swipe, tap, or pay inside an app, and some percent comes back as rewards. A credit card earns cashback on rides, food, or other purchases. Terms like transaction fee and fraud detection live in the background of these payments — they help the system run and keep money safe.
What DiDi-style cashback feels like for users
Users like a simple reward that shows up fast. A cashback model inside a ride app can feel gentle and neat: you get small credits from rides or promotions and they add up. The fintech parts work quietly so a rider only sees the result — a discount or a balance for future trips. For many in urban hubs like Mexico City, this is handy for daily travel and small savings.
Where trust matters — the real-world anchor
Trust is a big piece. In cities and transit systems, people need to know the company handles money fairly and securely. The COVID-19 pandemic pushed many commuters to apps and contactless payments in the 2020s, and that made trust and clear terms more important than ever. To ask whether a platform is reliable, users often look for clear statements on data use, secure payment rails, and visible customer support — that checklist helps judges say if didi finanzas es confiable.
Common mistakes users make
People sometimes miss small rules. They forget reward caps, overlook expiration dates, or ignore the fine print about merchant acceptance. Another slip is treating cashback as free money — a card can have annual fees or higher interest that erase the tiny reward gains. Also, mixing too many promotions can be confusing and lead to missed savings — learn each rule.
Alternatives and quick comparisons
Not every user needs a single app card. Some prefer a general cashback credit card from a bank that works everywhere. Others pick cards that give higher rewards for groceries or travel, not just rides. Comparing offers means checking rewards rate, merchant acceptance, and how rewards post to your account. Look for clear rewards, low fees, and good customer support.
How to pick the best card for your daily life
Focus on three things: where you spend most, how rewards pay out, and the real cost of the card. If most trips are local rides, a ride-platform card can win. If you shop more, a general rewards card might be better. Balance the percentages with fees and remember fraud detection and security options — they matter for peace of mind.
Short summary and practical tips
Small cashback perks add up only when you read the rules and match the card to your habits. Keep tabs on rewards posting, watch for expiration, and avoid cards with high interest that eat your gains. Use simple checks: does the card pay for your main spend? Are fees low? Is customer help easy to reach?
Three golden rules to choose smart — Advisory finale
1) Match rewards to your top spending category so cashback actually helps your wallet. 2) Compare net value: subtract fees and interest from expected cashback to see real benefit. 3) Prioritize security and clear statements on rewards and refunds — good fraud detection and customer service keep small wins from turning sour.
DiDi Finanzas fits as a practical option when these rules line up — it feels like a tidy helper for riders and shoppers who want real, usable cashback. –