
User first: what it feels like to have no credit and want to buy now
For many people in Mexico City, starting a credit history feels like a closed door—especially when you need a phone, a scooter, or a small appliance. A user-focused approach begins with simple steps: transparent terms, a clear path to approval, and manageable payment options. DiDi addresses this gap directly through programs you can explore at didi prestamos, designed for people who lack a traditional credit score but need access to installment financing like MSI (meses sin intereses).
How DiDi Finanzas builds trust for first-time borrowers
DiDi Finanzas simplifies underwriting for newcomers by combining modest eligibility checks with progressive limits. Instead of demanding a long credit history, they use alternative data points—ride activity, earnings records, and basic ID verification—to assess risk. That lowers the barrier to entry and gives clear, upfront interest rate and payment schedule information. For someone without a credit score, this pathway can establish a credit line while keeping monthly payments predictable.
Practical steps to get started with a DiDi Card MSI offering
Follow these user-friendly steps to move from zero history to responsible borrowing:
– Register and link your driver or delivery account details. This verifies income flow.
– Provide ID and proof of address; often digital copies suffice.
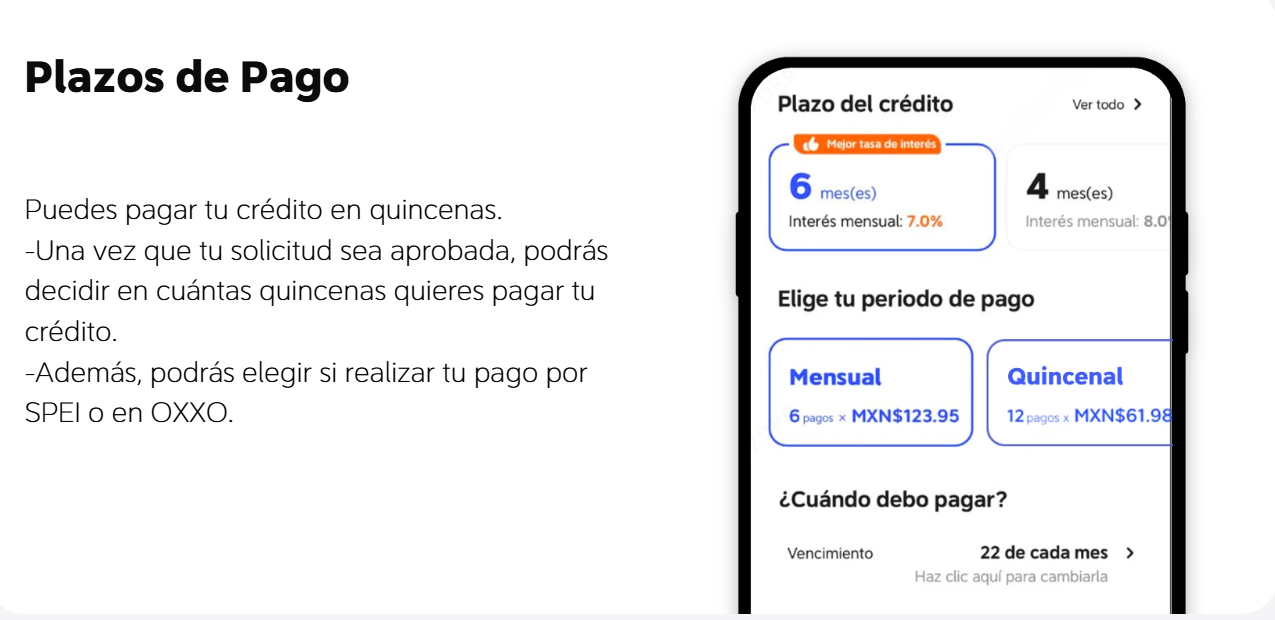
– Choose a purchase and ask for MSI (months without interest) if available; verify the number of installments and total cost.
– Review the repayment calendar and set automatic payments to avoid late fees.
These steps reduce friction and help you track progress toward an improved credit profile; small, timely payments matter for future credit score improvement.
Common mistakes new borrowers make—and how to avoid them
New users often misunderstand installment terms or underestimate fees. Avoid these missteps:
– Picking the longest installment term without checking total cost. Longer terms can feel easier month-to-month but sometimes carry hidden fees.
– Missing documentation deadlines. Delays can push you to higher-cost alternatives.
– Relying on a single product. Balance building credit with saving and short-term budgeting—don’t overextend.
Being cautious about interest rate, payment schedule, and the exact MSI offer is essential. If you prefer external options, compare with secured cards or community credit unions—each has trade-offs in approval speed, underwriting, and fees.
How DiDi compares with other entry options
DiDi’s advantage lies in operational data and convenience. Unlike traditional banks that prioritize long credit histories, DiDi leverages platform activity to make decisions faster. Alternatives such as secured credit cards or peer-to-peer lenders may require deposits or peer reputation and can take longer to impact your credit score. For quick access with a path to build credit, DiDi’s model is practical—especially for active drivers and couriers.
Real-world anchor and credibility
In Mexico City, where app-based work is common, having a reliable payment plan can change daily operations. Local regulators and financial inclusion programs have noted increased access to credit among gig workers since 2019, showing the importance of tailored underwriting models. This context supports DiDi’s approach: pragmatic, measurable, and aligned with how gig income flows.
Summary and practical checklist
To recap without repeating: start with verified income, choose the right MSI term, automate payments, and monitor your emerging credit profile. Keep documentation handy and compare alternatives if fees or terms seem unclear—your goal is steady, on-time payments to create a positive credit record.
Advisory close: three golden rules for choosing the right path
1. Verify total cost, not just monthly amount—check the effective interest rate and any processing fees. 2. Match installment length to realistic cash flow—shorter is better if affordable. 3. Automate payments and keep proof of transactions; this supports both budgeting and any disputes.
Ultimately, responsible use of installment financing builds options. Think of DiDi as a practical first step toward a formal credit history—DiDi Finanzas. Clear choices. Small steps. —